Investing for Beginners: A Complete Guide to Building Wealth
New to investing? Learn the basics of investing, how it works, different investment options, common mistakes, and how to start building long-term wealth with confidence.

Key takeaway
New to investing? Learn the basics of investing, how it works, different investment options, common mistakes, and how to start building long-term wealth with confidence.
Some links are affiliate links. If you sign up we may earn a commission at no extra cost to you. See our disclosure. This is educational content, not financial advice.
Investing is one of the most effective ways to grow your money over time. Saving protects your finances; investing gives your money the chance to grow and, over the long run, possibly outpace inflation.
Many beginners never start because they think investing is too complicated, too risky or only for wealthy people. Investing well isn't about predicting the next winning stock or becoming an expert overnight. It's about understanding a few core principles, making informed decisions and sticking with it for many years. Whether you want to build wealth, prepare for retirement, buy a home or reach financial independence, learning how investing works is an important step.
This guide explains investing in plain language and covers what a beginner needs to know before making a first investment.
Quick answer
Investing means putting money into assets with the aim of growing their value over time. Saving focuses on keeping your money safe; investing means accepting some risk in exchange for the chance of higher returns over the long term. The best time to learn about it is before you invest your first dollar, because a solid foundation helps you decide well for years.
Investing well usually involves:
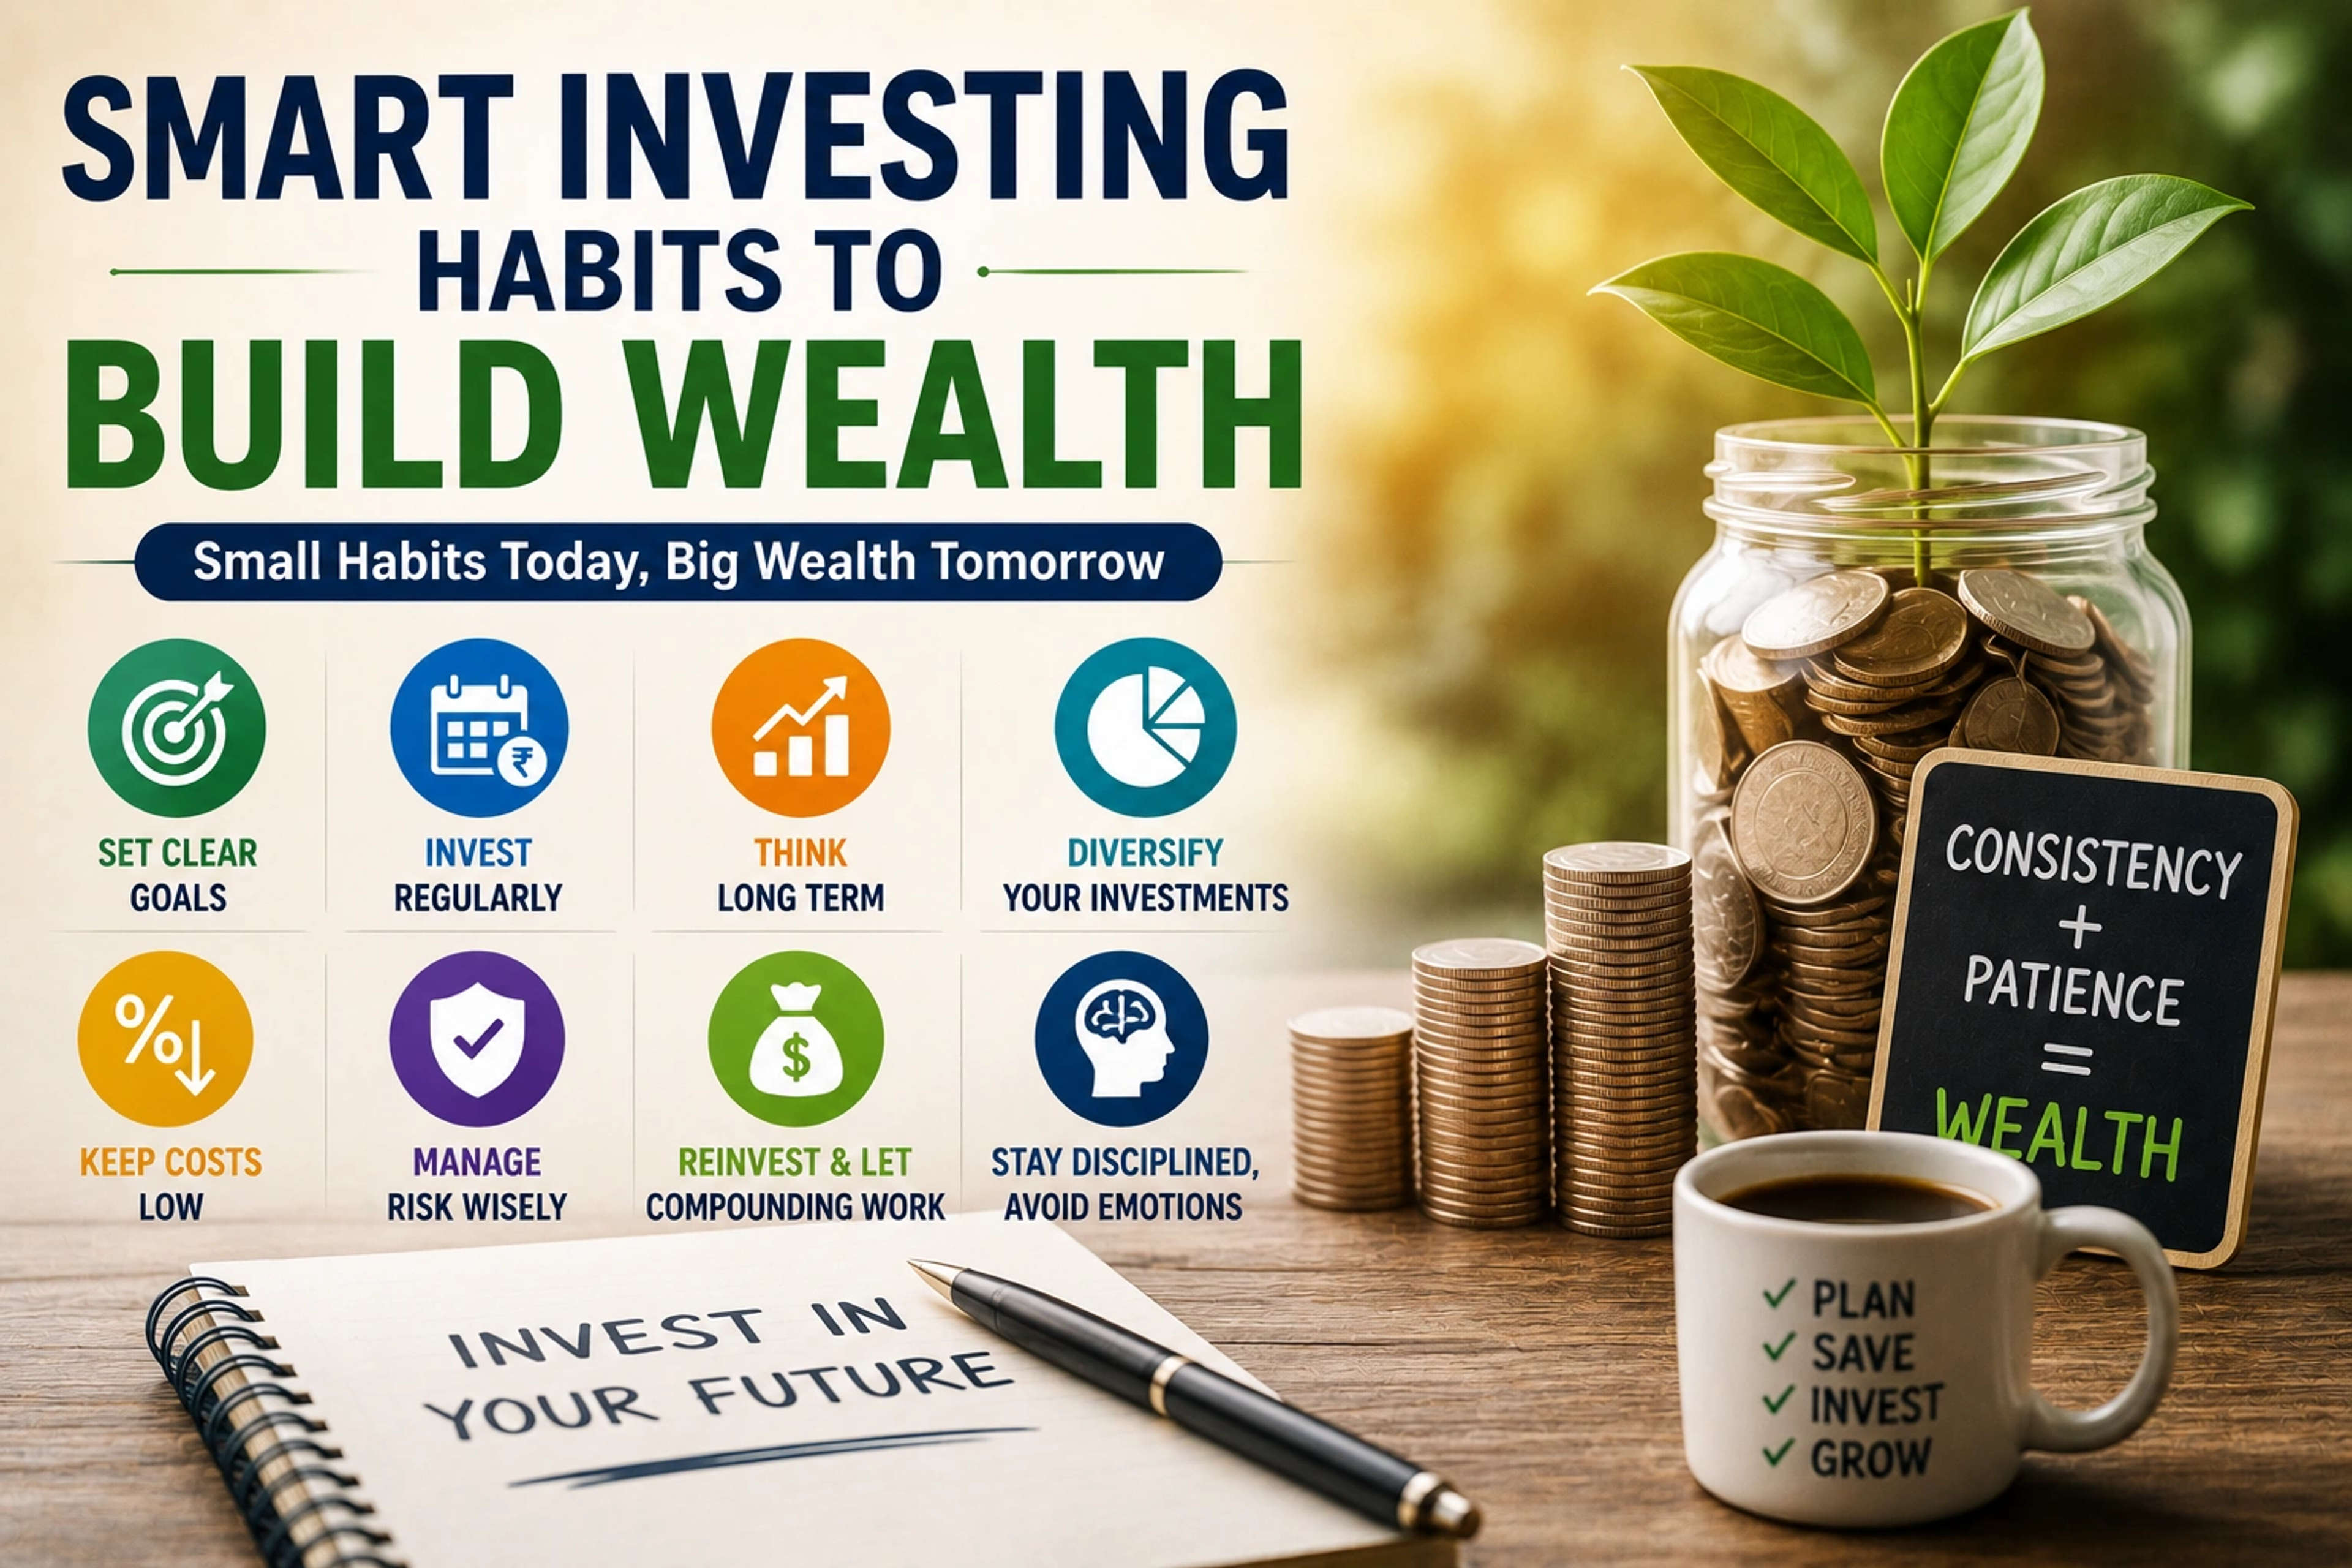
- Setting clear goals.
- Investing consistently.
- Diversifying.
- Thinking long term.
- Avoiding emotional decisions.
Common investment types at a glance
| Investment | Risk Level | Potential Return | Best For | Liquidity |
|---|---|---|---|---|
| Stocks | High | High | Long-term growth | High |
| Bonds | Low–Medium | Moderate | Stability and income | Medium |
| Index Funds | Medium | Moderate–High | Beginners | High |
| ETFs | Medium | Moderate–High | Diversified investing | High |
| Mutual Funds | Medium | Moderate | Hands-off investors | Medium |
| Real Estate | Medium–High | Moderate–High | Long-term wealth | Low |
| Certificates of Deposit (CDs) | Low | Low | Capital preservation | Low |
| Gold & Precious Metals | Medium | Varies | Diversification | Medium |
Why investing matters
Many people think saving is enough to build wealth. Saving is essential, but relying on it alone makes long-term goals harder to reach, partly because of inflation. The cost of goods and services generally rises over time, so if your money grows more slowly than prices, it buys less.
Investing gives your money a chance to grow through capital gains, dividends, interest or other returns, depending on the investment. Investing regularly over many years can help you work toward:
- Retirement.
- Buying a home.
- Paying for a child's education.
- Starting a business.
- Long-term financial security.
Investing always involves risk, but a thoughtful long-term approach has historically helped many people grow their wealth over long periods.
Saving vs investing
People often use the two words interchangeably, but they do different jobs.
| Saving | Investing |
|---|---|
| Focuses on protecting money | Focuses on growing money |
| Lower risk | Higher risk |
| Easier access to cash | May fluctuate in value |
| Best for short-term goals | Best for long-term goals |
| Lower potential returns | Higher potential returns |
A healthy financial plan usually includes both: savings for emergencies and short-term costs, and investments for goals that are several years away.
What can you invest in?
There are many ways to invest, and each type has a different purpose and level of risk. Here are the most common.
1. Stocks
A stock is a small share of ownership in a company. If the company does well, your investment may grow, and some companies also pay part of their profits to shareholders as dividends. Stocks have historically offered strong long-term growth, but their prices can swing a lot in the short term. They suit long-term investors who are comfortable with market ups and downs.
2. Bonds
A bond is essentially a loan to a government, local authority or company. In return, the issuer generally pays you interest for a set period and repays the principal at the end, depending on the bond's terms and the issuer's ability to pay. Bonds are usually less volatile than stocks, though they still carry risk. They suit investors who want more stability or income.
3. Index funds
Index funds aim to match the performance of a particular market index rather than beat it. Instead of picking individual companies, they spread your money across many holdings. Because they're diversified, fairly cheap and simple, they're often recommended as a starting point for beginners who want broad market exposure with little management.
4. Exchange-traded funds (ETFs)
ETFs are similar to index funds in many ways, but they trade on stock exchanges like individual shares. They can give you exposure to stocks, bonds, commodities or particular industries, and you can buy and sell them throughout the trading day. Many investors use them to build diversified portfolios; they suit people who want flexibility along with diversification.
5. Mutual funds
Mutual funds pool money from many investors and are professionally managed. Depending on the fund's objective, it may invest in stocks, bonds or a mix. They can suit investors who want a managed approach, though fees and strategies vary from fund to fund.
6. Real estate
Real estate investing means buying property for rental income, long-term growth in value or both. Compared with many financial investments, it usually needs more capital, ongoing maintenance and hands-on management. It suits long-term investors willing to manage physical property or explore real estate investment vehicles.
7. Gold and other precious metals
Precious metals are often seen as a way to diversify a portfolio. Their prices can swing a lot, and they don't produce income the way dividend-paying stocks or interest-paying bonds can, so they're better for diversification than as your main source of long-term growth.
Risk and reward
One of the first things every beginner should understand is that risk and potential reward go together. Investments with higher potential returns usually carry more risk, and lower-risk investments usually offer lower expected returns. That doesn't make high-risk investments better. The right choice depends on:
- Your goals.
- Your time horizon.
- Your income.
- Your emergency savings.
- How comfortable you are with market swings.
Knowing your own risk tolerance helps you choose investments that fit your situation rather than someone else's.
What is diversification?
Diversification means spreading your money across different assets instead of relying on one. Rather than putting everything into one company, a diversified portfolio might include:
- Stocks from different industries.
- Bonds.
- Index funds.
- International investments.
- Other asset types.
The aim is to limit the damage if any one investment does badly. Diversification helps manage risk, but it doesn't remove the chance of losing money.
How compound growth builds wealth
One of investing's biggest advantages is that you earn returns on your original money and on the returns you've already earned. This is compound growth, often described as one of the most powerful forces in long-term investing.
Say you invest some money and it earns a return. If you leave the earnings invested, future returns are calculated on both your original investment and the earlier gains, and over long periods that snowballs. Someone who starts investing in their twenties may put in far less money overall than someone who starts later and still end up with more, simply because their money had longer to compound.
You don't need to invest huge sums straight away. Starting early and investing consistently usually matters more than investing large amounts later. Time is an advantage every investor can use, and even modest amounts invested steadily over many years can grow a lot.
How much money do you need to start?
A common misconception is that you need thousands of dollars. Many investment platforms let beginners start with fairly small amounts, and some offer fractional investing, which lets you buy part of a share instead of a whole one. How much you start with matters far less than building the habit of investing regularly, so invest an amount that fits comfortably in your budget rather than waiting until you have a large balance.
Before investing, though, make sure you've taken care of a few priorities:
- Pay your essential living costs.
- Build an emergency fund.
- Pay down or manage high-interest debt where it makes sense.
- Make a basic monthly budget.
Investing should strengthen your finances, not add stress.
Should you pay off debt before investing?
It depends largely on the kind of debt. High-interest debt, such as many credit cards, gets very expensive over time, and paying it down can give you a more predictable benefit than investing while the interest keeps piling up. Lower-interest debt may call for a different approach depending on your goals, cash flow and situation.
Many people work on both rather than treating them as competing priorities: they build an emergency fund, pay down expensive debt and start investing for the long term once their finances are more stable. If you're unsure, a qualified financial professional can look at your circumstances.
A step-by-step guide to your first investment
Step 1: define your goal
Decide why you're investing, whether for retirement, a home, long-term wealth, education or financial independence. Your goal shapes which investments make sense.
Step 2: decide your time horizon
Ask when you'll need the money. Someone investing for retirement in 30 years will usually invest differently from someone saving for a home in five. Generally, the longer your horizon, the more short-term ups and downs you can ride out.
Step 3: understand your risk tolerance
Risk tolerance is how comfortable you are with temporary falls in your investments. Some people stay calm in a downturn; others get anxious when values move. Knowing where you stand helps you build a portfolio you'll actually stick with through different markets.
Step 4: choose an account
Depending on where you live, you may be able to choose from:
- Standard brokerage accounts.
- Retirement accounts.
- Tax-advantaged investment accounts.
- Education savings accounts.
The options and their tax treatment vary by country, so learn the rules where you live.
Step 5: choose your investments
Beginners often try to find the perfect stock. Many experienced investors build diversified portfolios from broad market investments instead of relying on individual companies. Whatever you choose, make sure you understand what you're investing in, why, what the risks are and how it fits your long-term plan.
Step 6: invest consistently
Investing once helps; investing regularly is usually more powerful. Many investors automate monthly contributions so investing becomes a habit rather than something they have to remember. Consistency often matters more than trying to pick the perfect moment.
What is dollar-cost averaging?
Dollar-cost averaging means investing a fixed amount at regular intervals, whatever the market is doing. Instead of waiting for the perfect moment, you might invest the same amount every month. When prices are high, your money buys fewer shares; when they're low, it buys more. Over time this can soften the effect of short-term swings and take much of the emotion out of investing. It doesn't guarantee profits or protect against losses, but many long-term investors use it because it keeps them consistent.
Asset allocation
Asset allocation is how your money is split between different types of assets, such as:
- Stocks
- Bonds
- Cash equivalents
- Real estate
- Other investments
The right split depends on:
- Your age.
- Your goals.
- Your time horizon.
- Your risk tolerance.
Someone saving for a retirement decades away may choose a different mix from someone close to retiring. No single allocation is right for everyone; the aim is a portfolio that reflects your situation rather than a copy of someone else's.
Common investing strategies
There are many ways to invest well. Here are some of the most common.
Buy and hold means buying investments and keeping them for many years instead of reacting to short-term market moves. It's one of the simplest and most widely used long-term strategies.
Index investing means using funds that track a broad market index instead of picking individual companies. It gives you diversification with little ongoing management.
Dividend investing means focusing on companies that pay part of their profits to shareholders, often ones with a history of steady payments, though dividends are never guaranteed.
Growth investing means focusing on companies you think have strong potential to expand. These can swing more in price than more established companies.
Value investing means looking for investments you believe are trading below what they're really worth. It takes patience and careful research.
Building your first portfolio
A beginner's portfolio doesn't need to be complicated; many successful investors prefer simple portfolios they understand well. Focus on:
- Diversification.
- Your long-term goals.
- Consistency.
- Reasonable costs.
- Regular reviews rather than constant changes.
Resist buying and selling on headlines or market predictions, and build a strategy you can follow confidently whatever the market does. A simple plan you stick with usually beats a complicated one you abandon after a few months.
Common beginner mistakes
Every investor makes mistakes. What usually separates successful investors from the rest is learning from them and avoiding expensive habits, not intelligence. Many beginners lose money because of emotional or poorly informed decisions rather than because they picked the wrong investment.
1. Waiting for the perfect time
Many beginners spend months or years waiting for the right conditions, telling themselves they'll invest after the market falls, next year or once the economy improves. Predicting the market consistently is extremely hard, even for professionals. Investing thoughtfully matters, but waiting indefinitely costs you time your money could have spent growing. Invest consistently according to your plan instead of trying to predict the market.
2. Chasing recent winners
Headlines about a stock that doubled can make anyone feel left out, and that often leads beginners to buy after the price has already shot up. Past performance doesn't guarantee future results, and what rises fast can fall fast. Base your decisions on research and your long-term goals, not recent headlines.
3. Investing without research
Buying something because a friend, influencer or social media post recommended it is rarely a good strategy. Before investing, ask what the investment actually does, how it makes money, what the risks are and why you're buying it. If you can't answer, learn more first.
4. Letting emotions decide
Markets naturally rise and fall. Some investors panic in a downturn and sell everything; others get carried away in a strong market and invest more than they planned. Decisions driven by fear or excitement usually turn out badly over time. Make your plan before emotions get involved and stick to it where you can.
5. Not diversifying
Putting all your money into one company or industry greatly increases your risk, because even excellent businesses go through hard times. Spread your money across different companies, industries and asset types according to your goals, so one poor performer does less damage.
6. Checking your portfolio constantly
Many beginners check their investments several times a day. Short-term price moves are normal and don't necessarily say anything about long-term value, and constant checking adds stress and encourages unnecessary trading. Unless you're an active trader, reviewing periodically is usually enough.
7. Expecting quick results
Investing is a long-term process, and many successful investors spent years building their portfolios before seeing big results. Trying to double your money quickly usually means taking unnecessary risks. Aim for steady progress instead of overnight success.
Investment fees
Fees look small, but over decades even a minor annual fee can make a real difference to your returns. Common fees include:
- Account maintenance fees.
- Fund expense ratios.
- Trading commissions.
- Advisory fees.
- Transaction charges.
Not every investment has all of these, and fee structures vary between providers, so find out exactly what you'll pay before you invest. A cheaper investment isn't automatically better, but always weigh fees alongside performance, diversification and your goals. Small differences between platforms today can add up over the long term.
Taxes and investing
Taxes are an important part of investing, and the rules vary a lot depending on where you live and what you own. Investments can produce:
- Capital gains.
- Dividend income.
- Interest income.
Each may be taxed differently under your country's laws, and some countries offer tax-advantaged accounts to encourage long-term investing. You don't need to memorise the rules, but do remember that investment returns can have tax consequences. As your portfolio grows, consider talking to a qualified tax professional or checking guidance from your local tax authority.
How often should you review your portfolio?
Reviewing your investments is important; obsessing over them isn't. For most long-term investors, a review every few months, or after a major life event, is enough. Life events that call for a review include:
- A big rise or fall in income.
- Marriage.
- Having children.
- Buying a home.
- Planning for retirement.
- A major change in your goals.
At each review, ask whether the portfolio still matches your goals, whether your risk tolerance has changed, whether you're investing consistently, whether your asset allocation still makes sense and whether you need to rebalance. Stay informed without reacting to every market move.
Investment myths debunked
Myth 1: investing is only for wealthy people
Many platforms let you start with fairly small amounts, and building wealth usually starts with consistency, not a large first investment.
Myth 2: you need to be an expert
Education matters, but you don't need a finance degree to invest well for the long term. Learning the fundamentals and making informed decisions is usually enough for beginners.
Myth 3: investing is the same as gambling
Gambling depends mostly on chance. Investing means buying assets you expect may grow in value over time, although returns are never guaranteed, and responsible investing relies on research, diversification, patience and long-term planning.
Myth 4: you have to pick winning stocks
Many investors build diversified portfolios without trying to pick individual winners. Investing in the broad market is a common long-term approach.
Myth 5: a market drop means you should sell everything
Market falls are a normal part of investing. Selling in every downturn can lock in losses and derail your long-term plan, which is why many experienced investors stick to their strategy instead of reacting to short-term swings.
Key takeaways
- Investing is a long-term way to grow wealth.
- Set clear goals before choosing investments.
- Diversification helps manage risk.
- Consistency usually matters more than timing the market.
- Compound growth rewards patience.
- Avoid emotional investing.
- Understand the fees before you commit your money.
- Keep learning as you go.
Final thoughts
Investing doesn't need perfect timing, advanced maths or insider knowledge. It needs patience, consistency and a willingness to keep learning. Every successful investor started as a beginner, and the most important step isn't finding the next great investment; it's building good habits you can keep for decades.
Start with clear goals, invest only once you understand what you're buying, diversify, keep costs reasonable and stay focused in good markets and bad. Investing is a marathon, not a sprint, and the decisions you make today can shape your finances for many years.
Frequently asked questions
How much should a beginner invest?
The right amount depends on your financial situation, budget, and goals. Many beginners start with an amount they can comfortably invest on a regular basis without affecting essential expenses.
Is investing risky?
Yes. All investments involve some level of risk, including the possibility of losing money. Different investments carry different levels of risk, which is why understanding your goals and diversifying your portfolio are important.
Should I invest every month?
Many long-term investors choose to invest regularly because it encourages discipline and reduces the temptation to time the market. The best approach depends on your financial circumstances and goals.
Can I lose all my money?
Some investments carry higher risks than others. Diversification, research, and long-term planning can help manage risk, but no investment is completely risk-free.
Should I invest before building an emergency fund?
Many financial professionals recommend establishing an emergency fund before making significant long-term investments so unexpected expenses don't force you to sell investments at an unfavorable time.